Get the Medicare Advantage

Discover the benefits and added coverage with Medicare Advantage, designed to give you tailored, comprehensive healthcare.

What is Medicare Advantage?

Medicare Advantage, or Medicare Part C, is a health insurance plan offered by private companies approved by Medicare. These plans provide at least the same coverage as Original Medicare (Part A and Part B) but often include additional benefits that Original Medicare does not offer. One of the most common additional benefits is prescription drug coverage (Part D), which is included in most Part C plans.

These extra benefits can sometimes be provided at no additional cost to you. This is because Medicare pays the insurance company a fixed amount to provide your healthcare coverage.

Let’s explore the eligibility, enrollment, and benefits of a Medicare Advantage plan.
Part A

Hospital Stays

Part B

Medical Coverage

Part C

Medicare Advantage

Part D

Prescription Drugs

Am I eligible for Medicare Advantage?

To qualify for a Medicare Advantage plan, you must first be eligible for Medicare and enrolled in both Medicare Part A and Part B. You cannot drop Part B, as doing so would result in the loss of your Advantage plan.

The primary requirement for Medicare Advantage plans is that you are already enrolled in Original Medicare (Parts A and B) and reside within the service area of the Part C provider you wish to join. Since 2021, individuals diagnosed with End Stage Renal Disease (ESRD) can also enroll in most Medicare Advantage plans, which was not possible previously.

The eligibility criteria for Medicare Advantage are the same as those for Original Medicare. You must be a U.S. citizen or a permanent resident for at least five consecutive years and reside in the plan’s service area for six months each year.
Medicare Advantage Enrollment

If you are eligible for Medicare, it’s important to know the specific times you can enroll in a Medicare Advantage plan. Here are the key enrollment periods:
This seven-month period starts three months before the month you turn 65 and ends three months after. If you are under 65 and receive Social Security disability, you qualify for Medicare in the 25th month of receiving Social Security benefits. In this case, you can enroll in a Medicare Advantage plan from three months before your month of eligibility until three months after.
Also known as the Annual Enrollment Period (AEP), this runs from October 15 to December 7 each year. During this time, you can enroll in, change, or drop your Medicare Advantage plan. Coverage for the plan you select will begin on January 1 of the following year.
This period allows you to switch from one Medicare Advantage plan to another or to return to Original Medicare. It occurs from January 1 to March 31 each year.
Certain events can trigger a Special Election Period, allowing you to make changes to your Medicare Advantage plan outside the usual enrollment periods. Common triggers include moving outside your plan’s service area, qualifying for extra help with prescription drugs, or moving into a nursing home. It’s best to consult with a licensed Medicare insurance agent to determine if you qualify for an SEP.

Need the right Medicare plan?

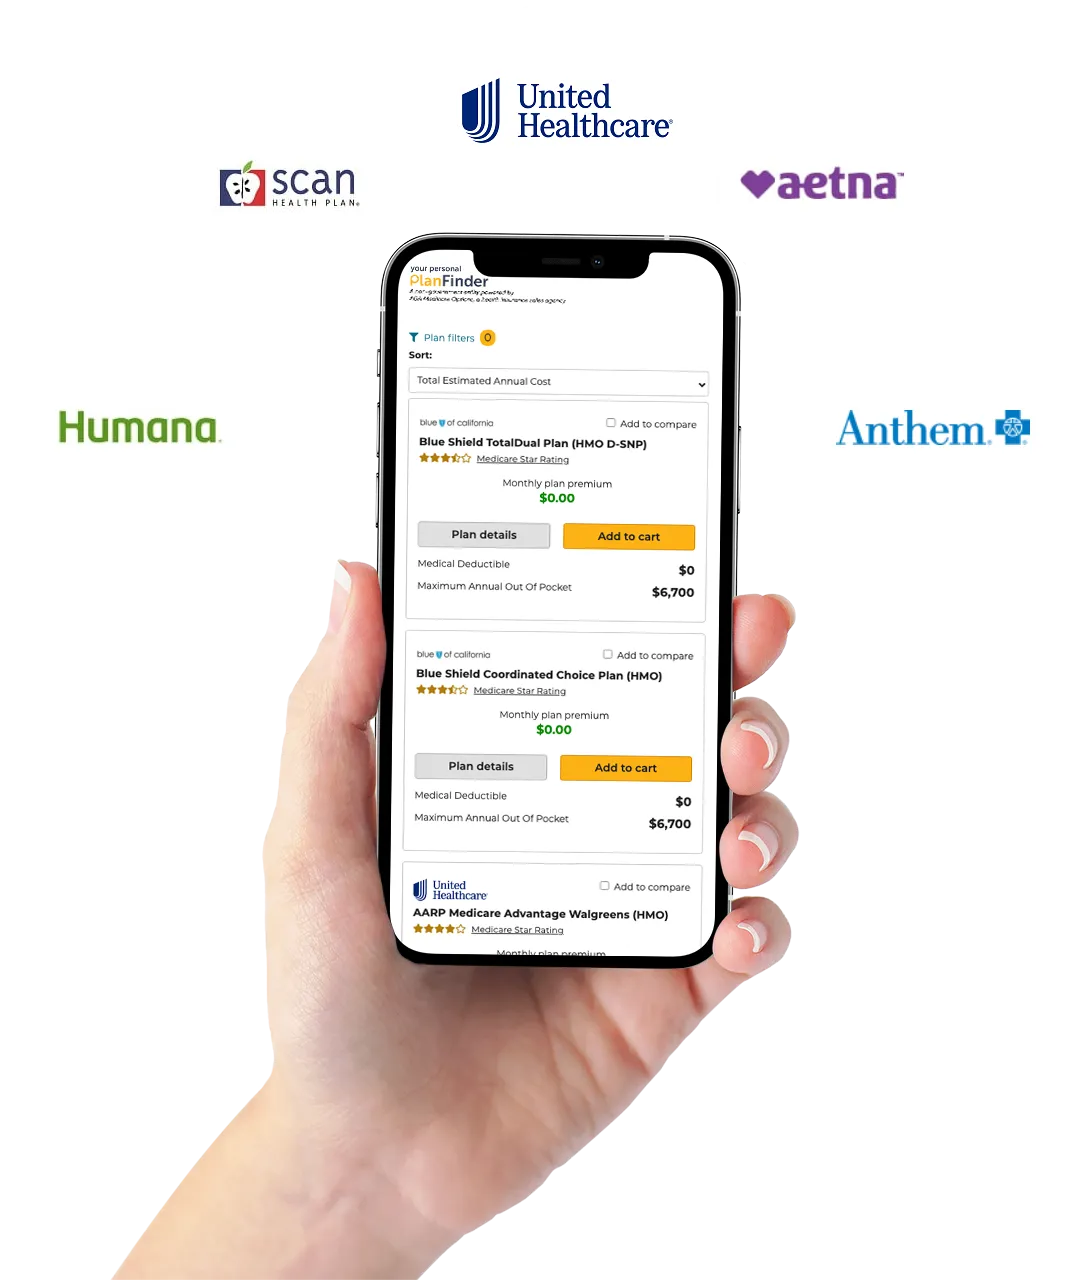
Sign up now for our FREE Plan Finder and save thousands of dollars with the right plan.

Medicare Advantage Coverage

Understanding what your Medicare Advantage (Part C) plan covers is crucial for maximizing your healthcare benefits. Medicare Advantage plans provide comprehensive coverage, including inpatient and outpatient care, similar to what is offered by Original Medicare (Parts A and B). However, they also offer additional benefits that can enhance your overall healthcare experience. In this section, we’ll explore the details of Medicare Advantage coverage, including the specific services covered and the extra benefits that may be available to you.

Inpatient Care Coverage

Medicare Advantage (Part C) provides coverage for inpatient care, similar to what is covered by Medicare Part A. This includes inpatient hospital care and care in a skilled nursing facility. Home health care is also covered under Part C, but hospice care benefits remain under Original Medicare (Part A and B).

Outpatient Care Coverage

Medicare Advantage covers the same outpatient services as Medicare Part B. This includes visits to primary care doctors and specialists, tests and X-rays, emergency ambulance services, mental health services (both inpatient and outpatient), durable medical equipment, vaccines, and therapies.

Additional Benefits

Medicare Advantage plans often include extra benefits that Original Medicare does not cover. These can include routine dental, vision, and hearing care, fitness programs like SilverSneakers, emergency medical assistance while traveling outside the U.S., and allowances for healthcare products.

Understanding Medicare Advantage Costs

Medicare Advantage plans, also known as Medicare Part C, come with a diverse range of costs. Many individuals opt for low-cost or even free plans, with $0 premium Medicare Part C plans available in 49 states. Conversely, some plans can cost several hundred dollars per month. Typically, more expensive plans offer enhanced benefits, such as access to a broader network of medical providers, more comprehensive coverage for specialized care, or better cost-sharing terms.

Key Factors Influencing Medicare Part C Costs

The costs associated with Medicare Part C are influenced by several factors, including premiums, deductibles, copayments, and coinsurance. These can vary widely, with monthly premiums and yearly deductibles ranging from $0 to several hundred dollars. Here are some of the most significant factors affecting the cost of Medicare Part C plans:
Some Medicare Part C plans come with no monthly premium. However, even with a $0 premium plan, you are still responsible for paying the Medicare Part B premium.
Most Medicare Part C plans have both a medical plan deductible and a separate drug deductible. Some free Medicare Advantage plans offer a $0 plan deductible.
Co-payments are fixed amounts you pay for each doctor’s visit or prescription drug refill. Co-insurance is a percentage of the cost of services that you pay out of pocket after meeting your deductible.
The type of Medicare Advantage plan you choose (e.g., HMO, PPO, PFFS) can significantly impact your costs.
One key benefit of Medicare Part C plans is the out-of-pocket maximum, which caps the amount you will spend on covered services in a year.
Most Medicare Advantage plans are location-specific and depend on the provider’s network. Frequent travelers might face out-of-network medical bills.
Your annual gross income can also affect your Medicare Part C costs. Higher-income individuals typically face higher Medicare expenses.

Exploring the Types of Medicare Advantage Plans

Medicare Advantage plans, also known as Medicare Part C, come in various types to cater to different healthcare needs. Here, we’ll explore the main types: Health Maintenance Organization (HMO) plans, Preferred Provider Organization (PPO) plans, Private Fee-for-Service (PFFS) plans, and Special Needs Plans (SNP). Additionally, there is the Medicare Advantage Medical Savings Account (MSA) plan, which combines traditional benefits with a savings account for medical expenses.

Health Maintenance Organization
(HMO) Plans

To join an HMO plan, you must be enrolled in Original Medicare.
HMO plans cover hospital and medical insurance from Original Medicare. Most also include Part D (prescription drug coverage), along with dental, vision, and hearing services. Additional benefits may include fitness memberships or home meal delivery.
HMO plans require you to use a list of in-network providers for medical services. Out-of-network services typically result in higher out-of-pocket costs.
These plans may have their own monthly premiums, deductibles, and copayments. Copayments for primary care and specialist visits range from $0 to $50 per visit. After meeting the deductible, you usually pay 20% of Medicare-approved costs.
HMO plans offer simplicity by consolidating coverage into one plan and feature out-of-pocket maximums to limit annual expenses.

Preferred Provider Organization
(PPO) Plans

PPO plans allow you to visit any doctor, specialist, or healthcare facility, whether in-network or out-of-network, without requiring a referral.
These plans can have their own monthly premiums and deductibles. Copayments vary based on whether the provider is in-network or out-of-network. PPO plans have separate out-of-pocket maximums for in-network and out-of-network services.
The key benefit is the flexibility to choose your preferred healthcare providers and not needing referrals for specialists.

Private Fee-for-Service (PFFS) Plans

PFFS plans have a network of contracted providers who agree to treat members. If you use non-network providers for non-emergency services, your costs may be higher or the services may not be covered.
Some PFFS plans include prescription drug coverage.
You are not required to have a primary care doctor or obtain referrals to see specialists.

Special Needs Plans (SNP)

SNPs are designed for people with specific diseases or conditions, those living in institutions like nursing homes, those who require nursing care at home, those eligible for both Medicare and Medicaid, and individuals with certain chronic or disabling conditions.
These plans include Medicare Part D (prescription drug coverage) and often feature specialists tailored to specific conditions.
You must have a primary care doctor and obtain referrals for specialists.
Eligible individuals can enroll in SNPs at any time.

Medicare Advantage Medical Savings Account (MSA) Plans

MSA plans combine a high-deductible health plan with a medical savings account to help pay for medical expenses.
These plans offer benefits from Original Medicare along with additional perks.
Funds deposited into the savings account can be used to pay for qualified medical expenses.

Want to join our free webinar?

Learn about the unexpected costs that often catch beneficiaries off guard and how to avoid them.

See what customers are saying...

EXCELLENT
Google star 1Google star 2Google star 3Google star 4Google star 5
Based on 33 reviews
Posted on Google Google
Darcy Roy profile picture
Darcy Roy
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Great company. Denise and Lynn do a great job. very knowledgeable!
Posted on Google Google
Denise Pearson profile picture
Denise Pearson
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I have experienced the TRUE definition of Personal service so many times here. Along side is the professionalism and knowledge exhibited by these amazing brokers. I have and will continue to refer my friends to them.
Posted on Google Google
Linda Moore profile picture
Linda Moore
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
With the help of Denise Anderson, I recently changed my health insurance. Denise answered all questions with patience and concern for my anxiety. After over two years of NOT changing, I finally did change to a new carrier. Everything she told me was true. I could not be happier or more satisfied with my choice. Thank you Denise for your patience and guidance.
Posted on Google Google
Kathy Fess profile picture
Kathy Fess
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We have been dealing with Denise Anderson, our Medicare Representative for about two to three years now. She is outstanding and is always timely and thorough, as well as helpful, cheerful and kind. She is quite knowledgeable and finds us the best way to go with our Medicare. We enjoy meeting with her and always come away pleased.
Posted on Google Google
Arnie Cicerone profile picture
Arnie Cicerone
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Very good meeting covered everything in detail . Extremely knowledgeable and pleasant to talk to.
Posted on Google Google
David Schlick profile picture
David Schlick
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I needed to change healthcare plans and Denise helped me out a lot, hooked me up with just the right plan. I would recommend this business and its employees wholeheartedly. They have the right amount of experience and a lot of expertise. Denise asked me questions to narrow down my needs and interests and found a plan that fitted me perfectly and did it so quickly and without any issues.
Posted on Google Google
Paul Pekarsky profile picture
Paul Pekarsky
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
It was an absolute pleasure wading through the myriad of Medicare options with Denise as my guide. She is very knowledgeable, patient and helpful. She listened to all my questions and made sure I fully understood the answers. I would recommend Denise to anyone who has Medicare needs and questions.
Posted on Google Google
Norann King profile picture
Norann King
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
For the first time I used a insurance broker for my Medicare insurance. I’ve had Kaiser for years and been very disappointed, it was time for a change. I did my research and discovered Make Medicare Work best decision I’ve ever made! My brokers name is Denise Anderson, she has been amazing! I gave her the information she needed and what I was looking for and she narrowed it down, gave me several choices plus doctors to choose from if I wanted that list, she did all the work for me and I believe I made the right choice with her help. Denise made it so easy, do not hesitate to let Denice help guide you to the right insurance, hospital and doctors when making your medical policy choices.
Posted on Google Google
Jean Peacock profile picture
Jean Peacock
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Denise was so helpful and knowledgeable when we were deciding on our Medicare strategy. She helped us make a decision and worked overtime to get us information in a timely manner.
Posted on Google Google
Martin Axel profile picture
Martin Axel
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Denise Anderson is a wonder! Always available and always goes the xtra mile to assist. A great agent. A getter human.
Join the webinar

Whether you’re new to Medicare or looking to optimize your plan, this webinar will guide you through the essential details and help you avoid costly mistakes.

Looking for a better Medicare plan?

Finding a Medicare plan that is right for you has never been so easy. Get access to a licensed Medicare Agent and your Personal Plan Finder for FREE.

Join our free Medicare webinar

Learn everything you need to know about choosing the right Medicare plan. We’ll guide you through the options, explain the benefits, and answer all your questions. It’s easy to understand and designed to help you make the best choice for your health and finances!
DENISE ANDERSON
Founder, J Johnston Insurance
Skip to content