Medicare Part D is a federal prescription drug program managed by private insurance companies. Medicare beneficiaries can either enroll in a standalone Part D plan to enhance their Original Medicare benefits or choose a Medicare Advantage (Part C) plan that includes prescription drug coverage.
Prescription drug coverage is exclusively available through Part D plans or Medicare Advantage Prescription Drug plans (MAPD). Original Medicare (Parts A and B) does not cover medications typically obtained at your local pharmacy. Part D plans require a separate monthly premium and come with their own deductibles, copayments, and coinsurance costs.
Upon enrolling in a Part D plan, you’ll receive a distinct Part D insurance card, which you’ll need to present when refilling your prescriptions.
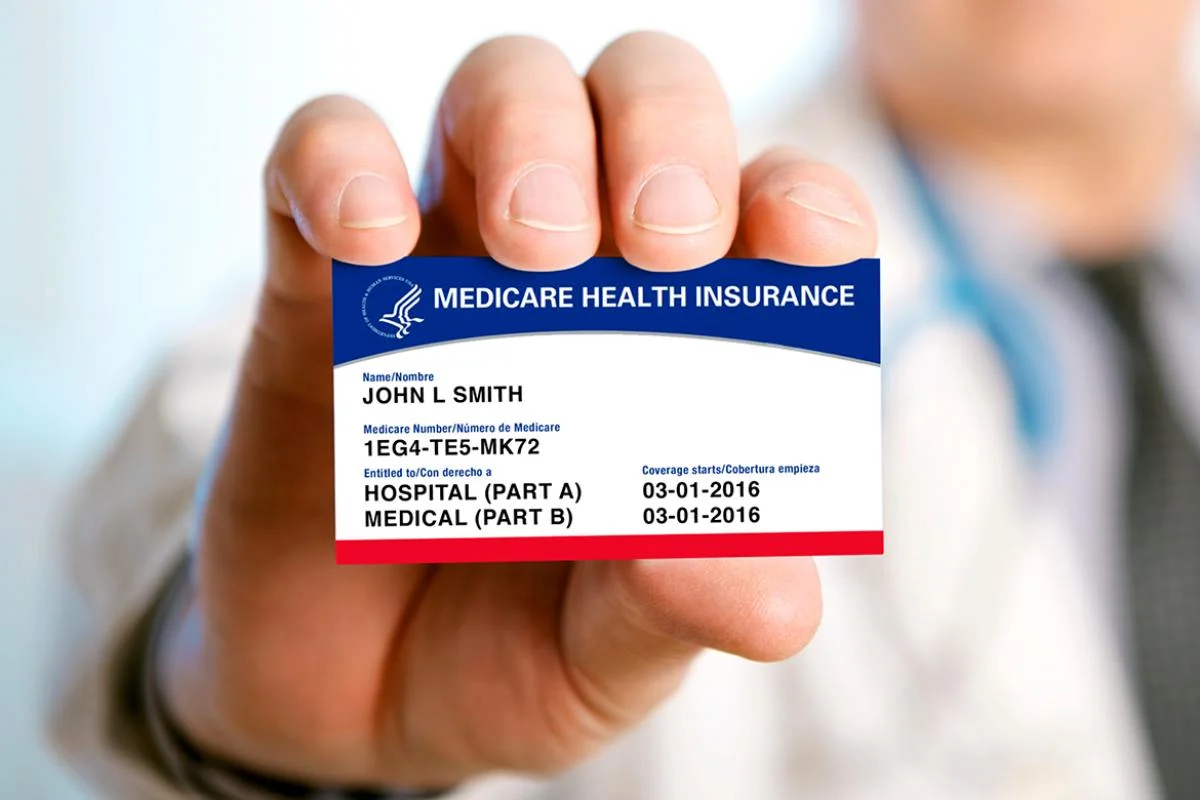
Medicare consists of four parts: A, B, C, and D. Parts A and B, known as Original Medicare, cover inpatient and outpatient medical costs, including some intravenous medications. However, they do not cover the prescriptions you typically get at your pharmacy.
Medicare Part C, or Medicare Advantage, includes various plans, some of which cover prescription drugs. These are called Medicare Advantage Prescription Drug plans (MAPD). If your Medicare Advantage plan includes prescription drug coverage, you do not need a separate Part D plan.
For those without an MAPD plan, a standalone Part D plan is essential for covering prescriptions obtained at the pharmacy. The only exception might be if you have prescription benefits through VA Healthcare or TRICARE for Life.
Even if you aren’t currently taking any prescriptions, enrolling in a Part D plan as soon as you are eligible is crucial. This is important for two reasons:
Enrolling in a Part D plan ensures you have the coverage you need for prescription medications and avoids penalties and gaps in coverage.
One of the most commonly encountered penalties in Medicare is the Part D penalty. Many people mistakenly believe that if they aren’t currently taking any medications, they don’t need to enroll in a prescription drug plan. This misconception can lead to costly penalties down the road.
If you go without prescription drug coverage for more than 63 consecutive days, you start accumulating a Part D penalty. Each month without coverage adds to the penalty, and once you enroll in a Part D plan, you’ll have to pay this penalty every month. Unfortunately, the penalty lasts as long as you have a Part D plan, which could be for the rest of your life.
The Centers for Medicare and Medicaid Services (CMS) calculate the Part D penalty. The penalty amount is determined by multiplying the number of uncovered months by 1% of the national base beneficiary premium. For 2023, the national base beneficiary premium is $32.74.
In addition to the penalty, you will also be responsible for the plan’s monthly premium, deductibles, and copayments or coinsurance. It’s important to note that the national base beneficiary premium typically increases each year, which means your penalty will also increase over time. You will pay this penalty every month for the rest of your life.
To avoid this financial burden, it’s crucial to enroll in a Part D plan as soon as you are eligible, even if you aren’t taking any medications currently. This proactive step can save you from long-term penalties and ensure you have coverage when you need it.
EXCELLENT Based on 33 reviews
 Posted on Google

 Darcy RoyGreat company. Denise and Lynn do a great job. very knowledgeable!Posted on Google
 Denise PearsonI have experienced the TRUE definition of Personal service so many times here. Along side is the professionalism and knowledge exhibited by these amazing brokers. I have and will continue to refer my friends to them.Posted on Google
 Linda MooreWith the help of Denise Anderson, I recently changed my health insurance. Denise answered all questions with patience and concern for my anxiety. After over two years of NOT changing, I finally did change to a new carrier. Everything she told me was true. I could not be happier or more satisfied with my choice. Thank you Denise for your patience and guidance.Posted on Google
 Kathy FessWe have been dealing with Denise Anderson, our Medicare Representative for about two to three years now. She is outstanding and is always timely and thorough, as well as helpful, cheerful and kind. She is quite knowledgeable and finds us the best way to go with our Medicare. We enjoy meeting with her and always come away pleased.Posted on Google
 Arnie CiceroneVery good meeting covered everything in detail . Extremely knowledgeable and pleasant to talk to.Posted on Google
 David SchlickI needed to change healthcare plans and Denise helped me out a lot, hooked me up with just the right plan. I would recommend this business and its employees wholeheartedly. They have the right amount of experience and a lot of expertise. Denise asked me questions to narrow down my needs and interests and found a plan that fitted me perfectly and did it so quickly and without any issues.Posted on Google
 Paul PekarskyIt was an absolute pleasure wading through the myriad of Medicare options with Denise as my guide. She is very knowledgeable, patient and helpful. She listened to all my questions and made sure I fully understood the answers. I would recommend Denise to anyone who has Medicare needs and questions.Posted on Google
 Norann KingFor the first time I used a insurance broker for my Medicare insurance. I’ve had Kaiser for years and been very disappointed, it was time for a change. I did my research and discovered Make Medicare Work best decision I’ve ever made! My brokers name is Denise Anderson, she has been amazing! I gave her the information she needed and what I was looking for and she narrowed it down, gave me several choices plus doctors to choose from if I wanted that list, she did all the work for me and I believe I made the right choice with her help. Denise made it so easy, do not hesitate to let Denice help guide you to the right insurance, hospital and doctors when making your medical policy choices.Posted on Google
 Jean PeacockDenise was so helpful and knowledgeable when we were deciding on our Medicare strategy. She helped us make a decision and worked overtime to get us information in a timely manner.Posted on Google
 Martin AxelDenise Anderson is a wonder! Always available and always goes the xtra mile to assist. A great agent. A getter human.